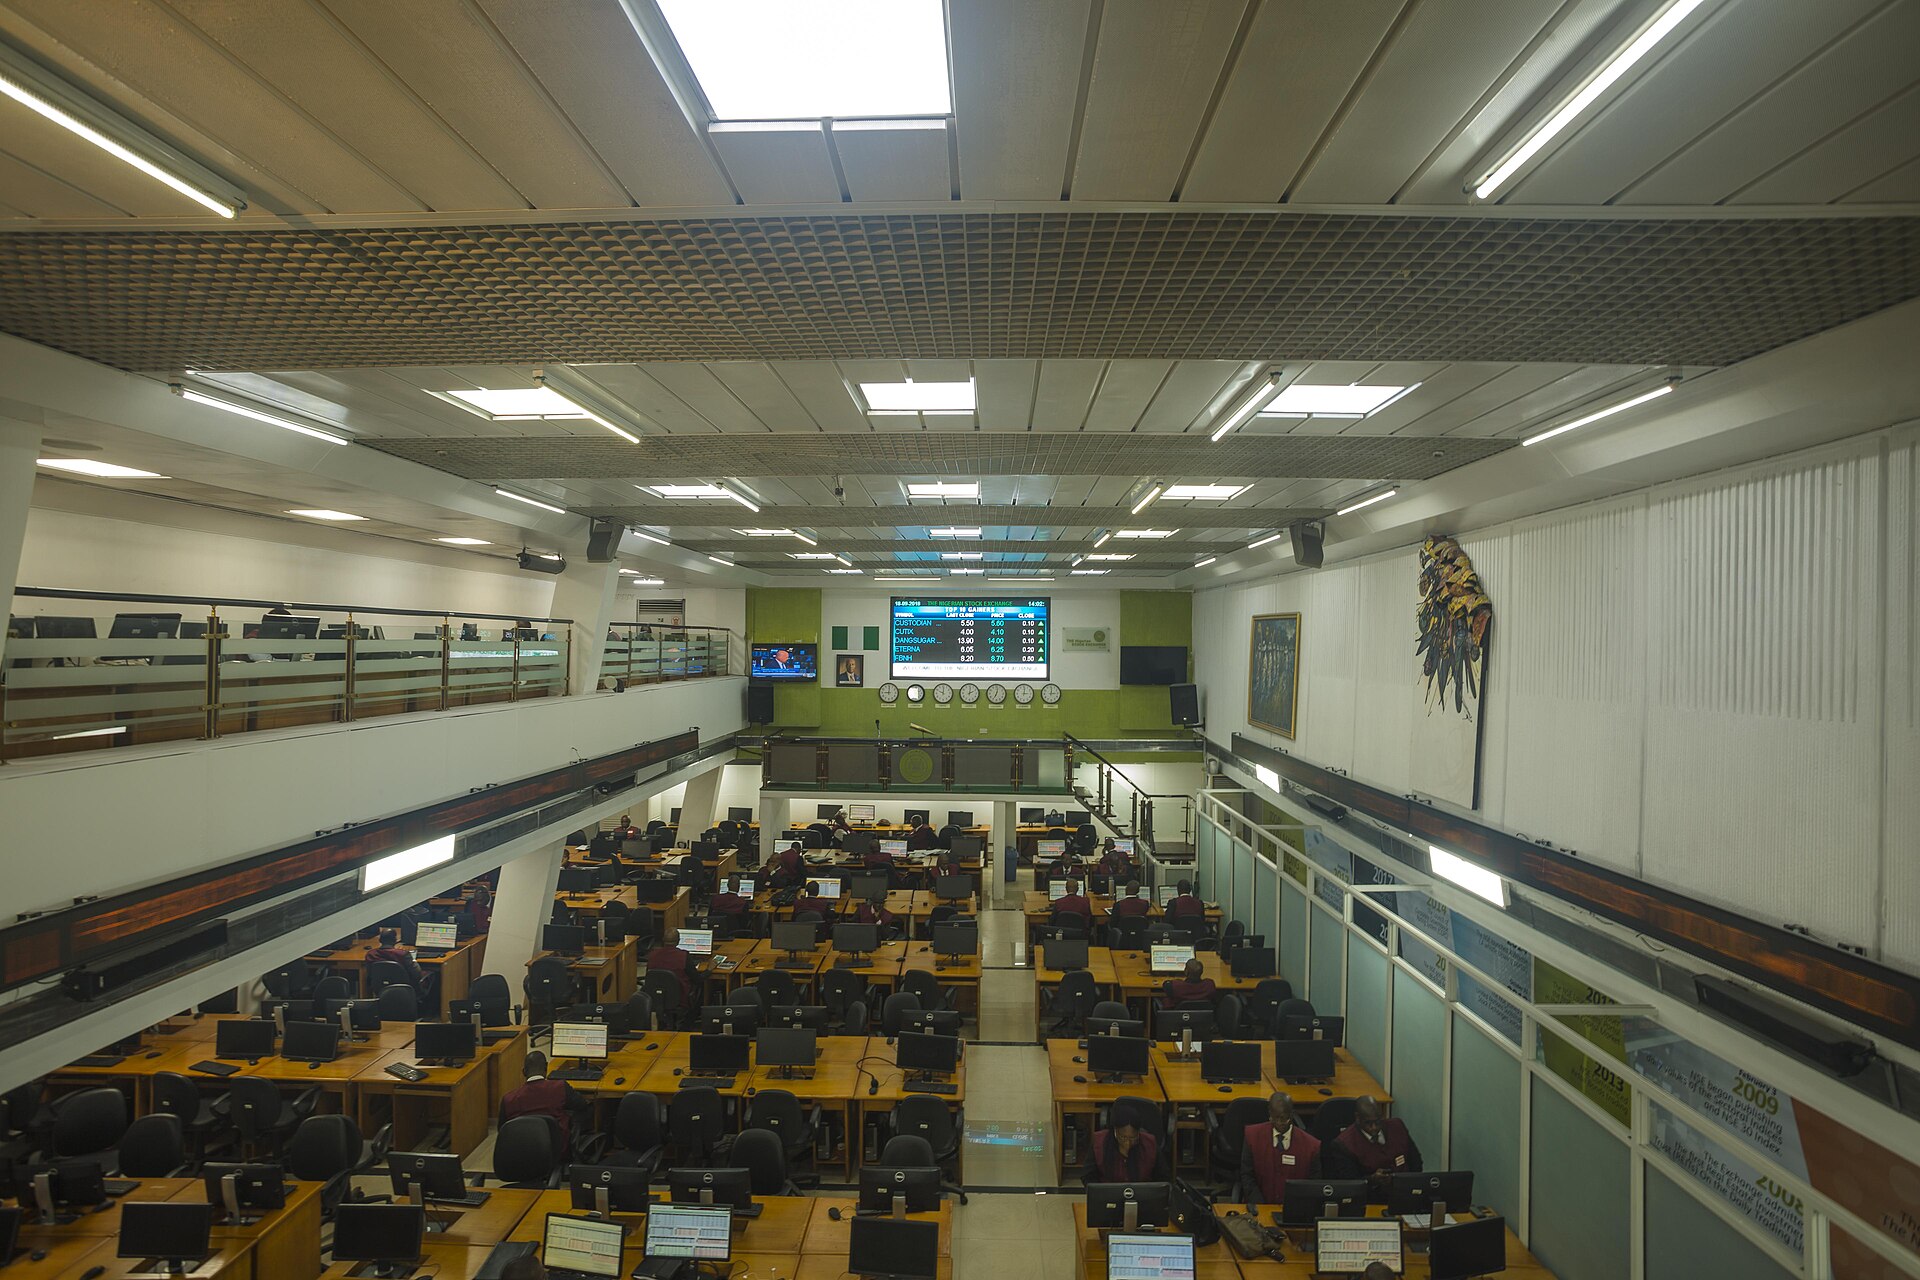

NGX All-Share Index traded almost flat on Tuesday after the previous session’s strong advance, with the All-Share Index at 251,330.26 points in a 10:30 a.m. WAT market update, up 39.72 points or 0.02%.
Koboterminal’s Tuesday market wrap put equity capitalisation at ₦163.19 trillion, an increase of ₦25.79 billion from Monday’s close. At the time of its snapshot, 11 stocks were advancing, six declining and two unchanged. Trading volume stood at 29.4 million shares, with 4,112 deals worth about ₦1.46 billion.
The session was still open when those figures were published, so they are an intraday reading rather than Tuesday’s final close. The modest move followed Monday’s 1.65% gain, which lifted the index to 251,290.54 points. The shift suggests a pause in the rally at the start of Tuesday’s trade, not a settled direction for the full session.
Small gains after a stronger Monday
Monday’s move had been led by industrial and financial counters. Dangote Cement rose 10% to ₦1,222.10 a share, while the market’s capitalisation increased by about ₦2.64 trillion to ₦163.16 trillion. Punch reported the advance alongside gains in several sectoral indices, including industrial goods and banking.
Tuesday’s much smaller index change came with narrower positive breadth in the early snapshot. Eleven advancers outnumbered six decliners, but the figures do not show a market moving uniformly in one direction. Index points and aggregate capitalisation can be heavily influenced by large listed companies, while individual share prices may diverge sharply from the benchmark.
NSLTECH led the gainers in the morning update, rising 10% to ₦0.77. Honeywell Flour and Caverton also recorded advances, while McNichols was among the day’s decliners. The report listed NSLTECH as the most active by volume and Stanbic IBTC as the leader by value at that point in the session.
What investors will watch
The next useful comparison is the official end-of-day print: whether the index holds above Monday’s close, whether market breadth broadens, and how much trading value accumulates by the finish. A single morning snapshot cannot establish that investor demand has weakened or that Monday’s rally has run out of steam. It does, however, show that the market opened the week’s second trading day close to the previous session’s level after a sizable one-day rise.
Investors also have to separate the benchmark from company-specific news. A near-flat headline index can sit alongside large moves in smaller counters, and one or two heavyweights can shift the aggregate more than a wider group of mid-cap names. That makes breadth, turnover and sector performance useful companions to the All-Share Index rather than optional footnotes.
For now, Tuesday’s published figures point to a market consolidating around 251,300 points in early trade. The session’s final direction remained unknown at the time of reporting; the numbers above should be read with their 10:30 a.m. timestamp.
The snapshot’s 39.72-point gain is small beside Monday’s 4,068-point jump, but the comparison is useful only with the time stamps in view. Monday’s figure is a completed close; Tuesday’s 10:30 reading captures a session still under way. The 29.4 million shares and ₦1.46 billion in value are likewise partial-session totals. They should not be compared directly with Monday’s full-day turnover as if both were complete. Market watchers will need the later official close and final volume before drawing conclusions about whether Tuesday represents a pause, a reversal or simply routine intraday movement.
The All-Share Index is a benchmark for listed equities as a group; its gain does not imply that every constituent is rising. The Tuesday snapshot showed 11 advancing counters against six declining ones, a positive but narrow reading of breadth at that time. Company-specific price moves and the weight of larger listings can still pull the benchmark away from the experience of a typical investor. That is why the final market breadth and sector breakdown will matter alongside the closing index.
Measured against Monday’s 251,290.54-point finish, the 10:30 reading was only about 0.016% higher. That calculation reinforces how little the index had moved in the early session; the previous day’s percentage gain was considerably larger. The final print, rather than this partial reading, will determine whether the market ended the day higher or gave back the small opening advance.
The conversation
0 comments
Join the discussion with a thoughtful response.